San Francisco Condo Buying Guide: What Buyers Should Know
Condo or TIC, HOA documents, reserves, retrofit and earthquake insurance, explained for California buyers.
By Lance Fulford5 min read
Buying a condominium in San Francisco means reading more than the listing. The building's finances, the type of ownership, its earthquake history and its insurance all shape what you are really buying, and how easily you will be able to sell later. This guide covers what California and San Francisco buyers should check, in the order it usually comes up.
First: is it actually a condominium?
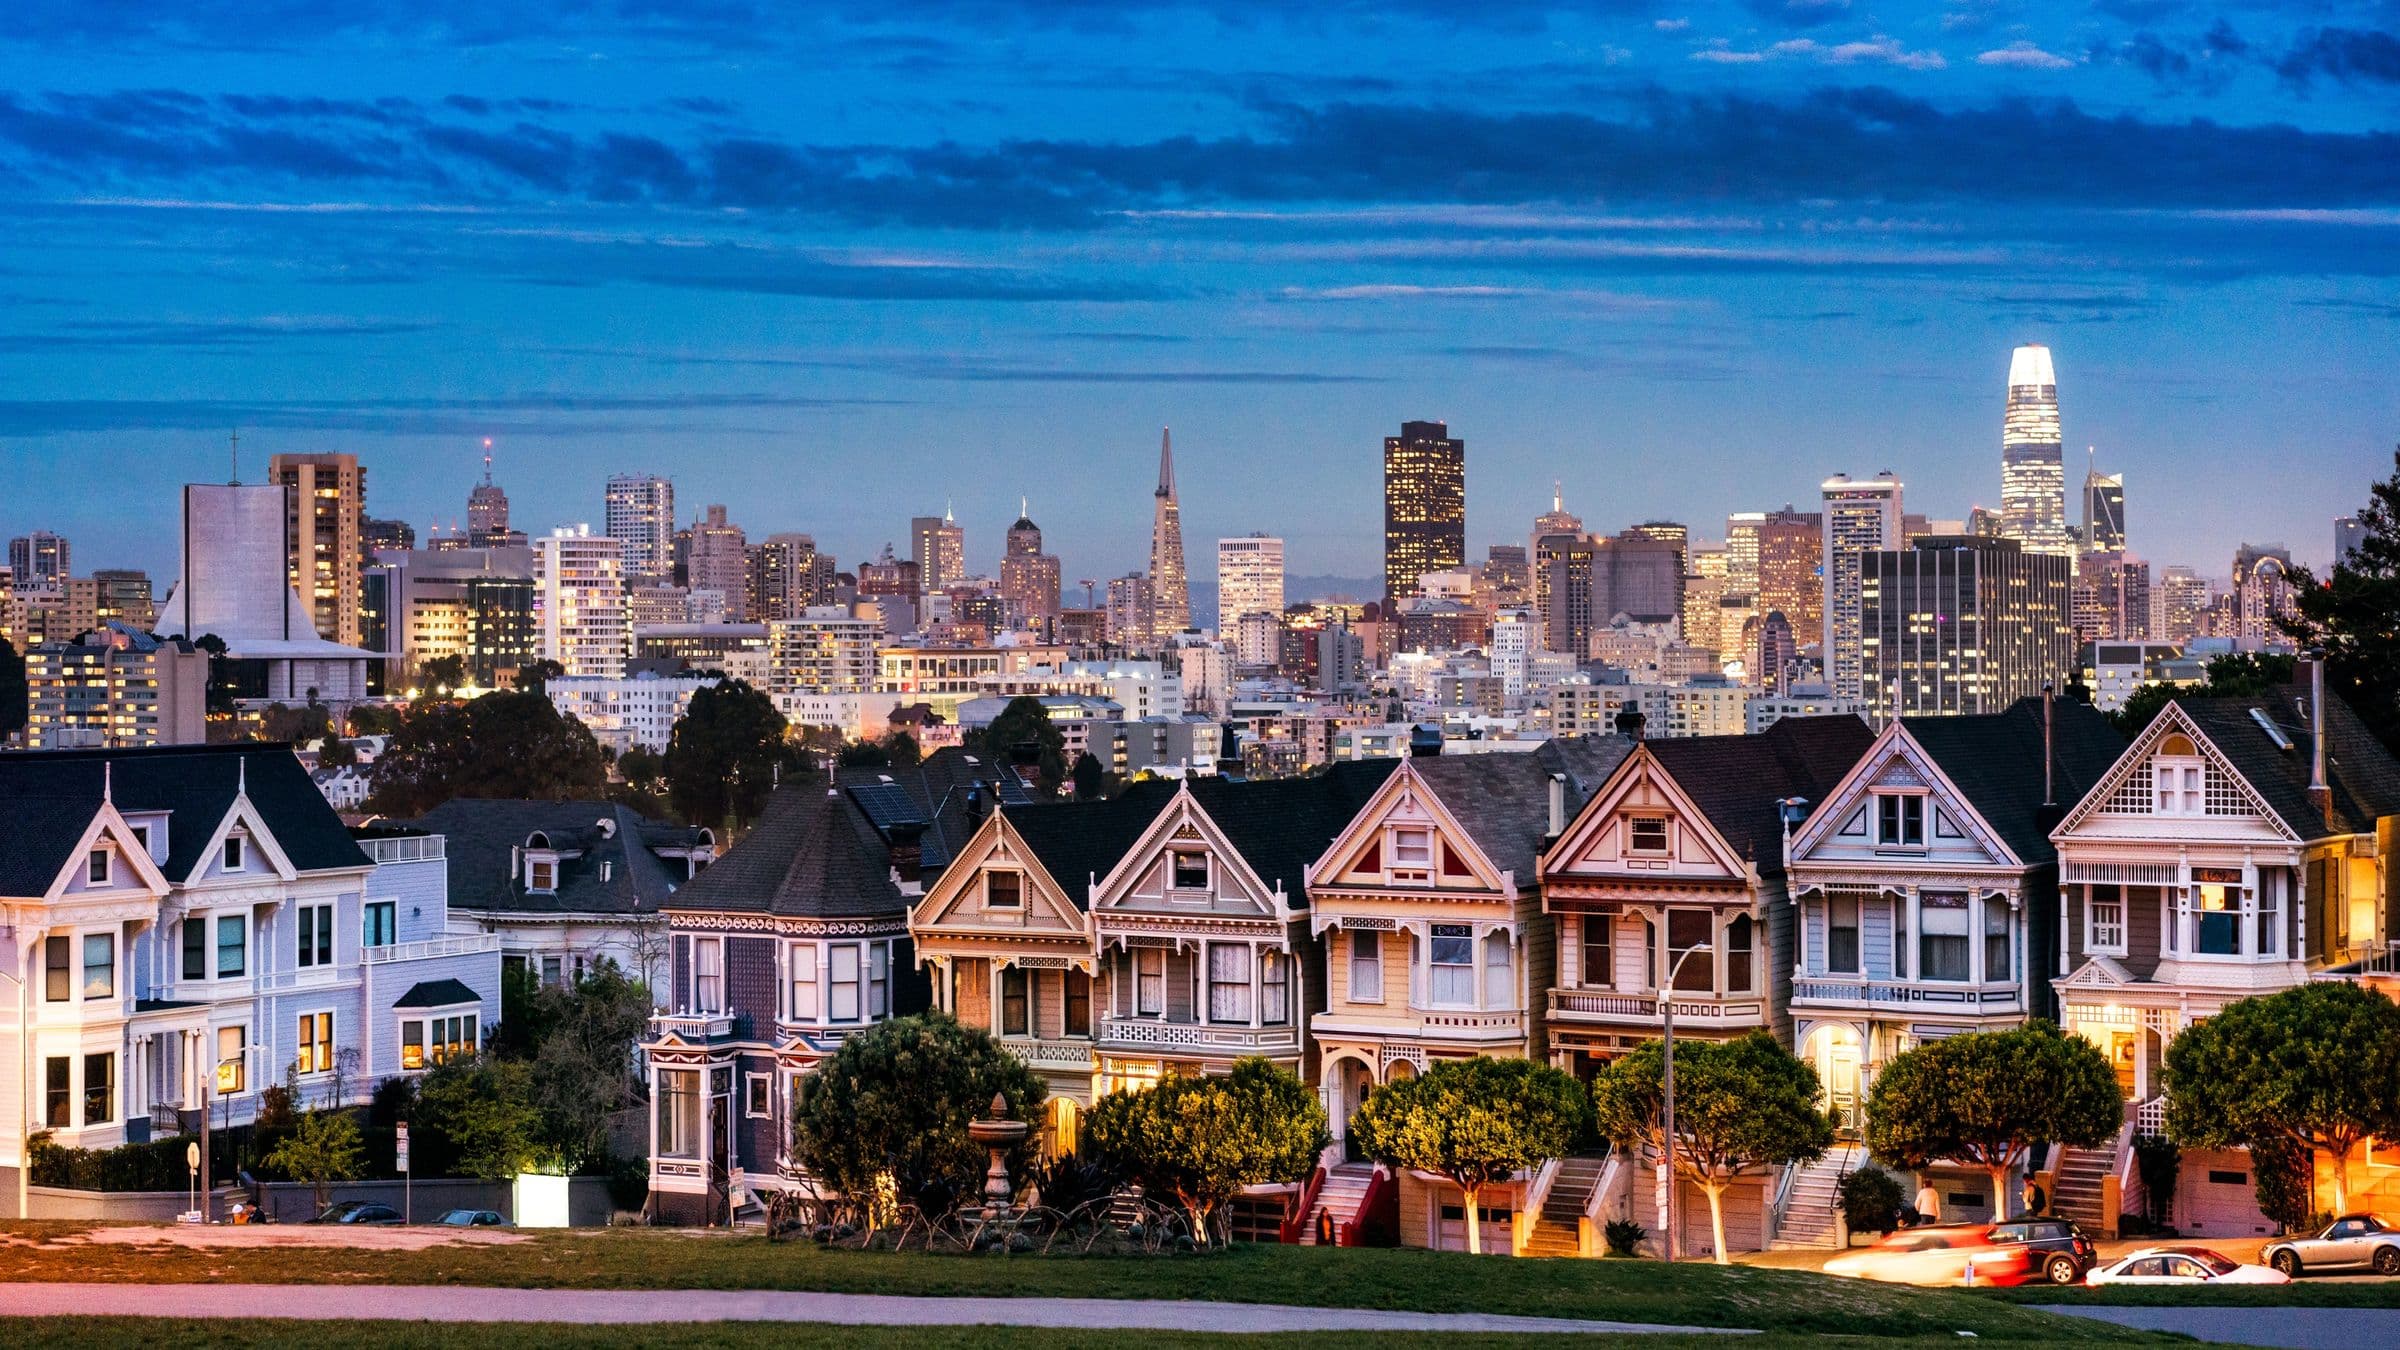
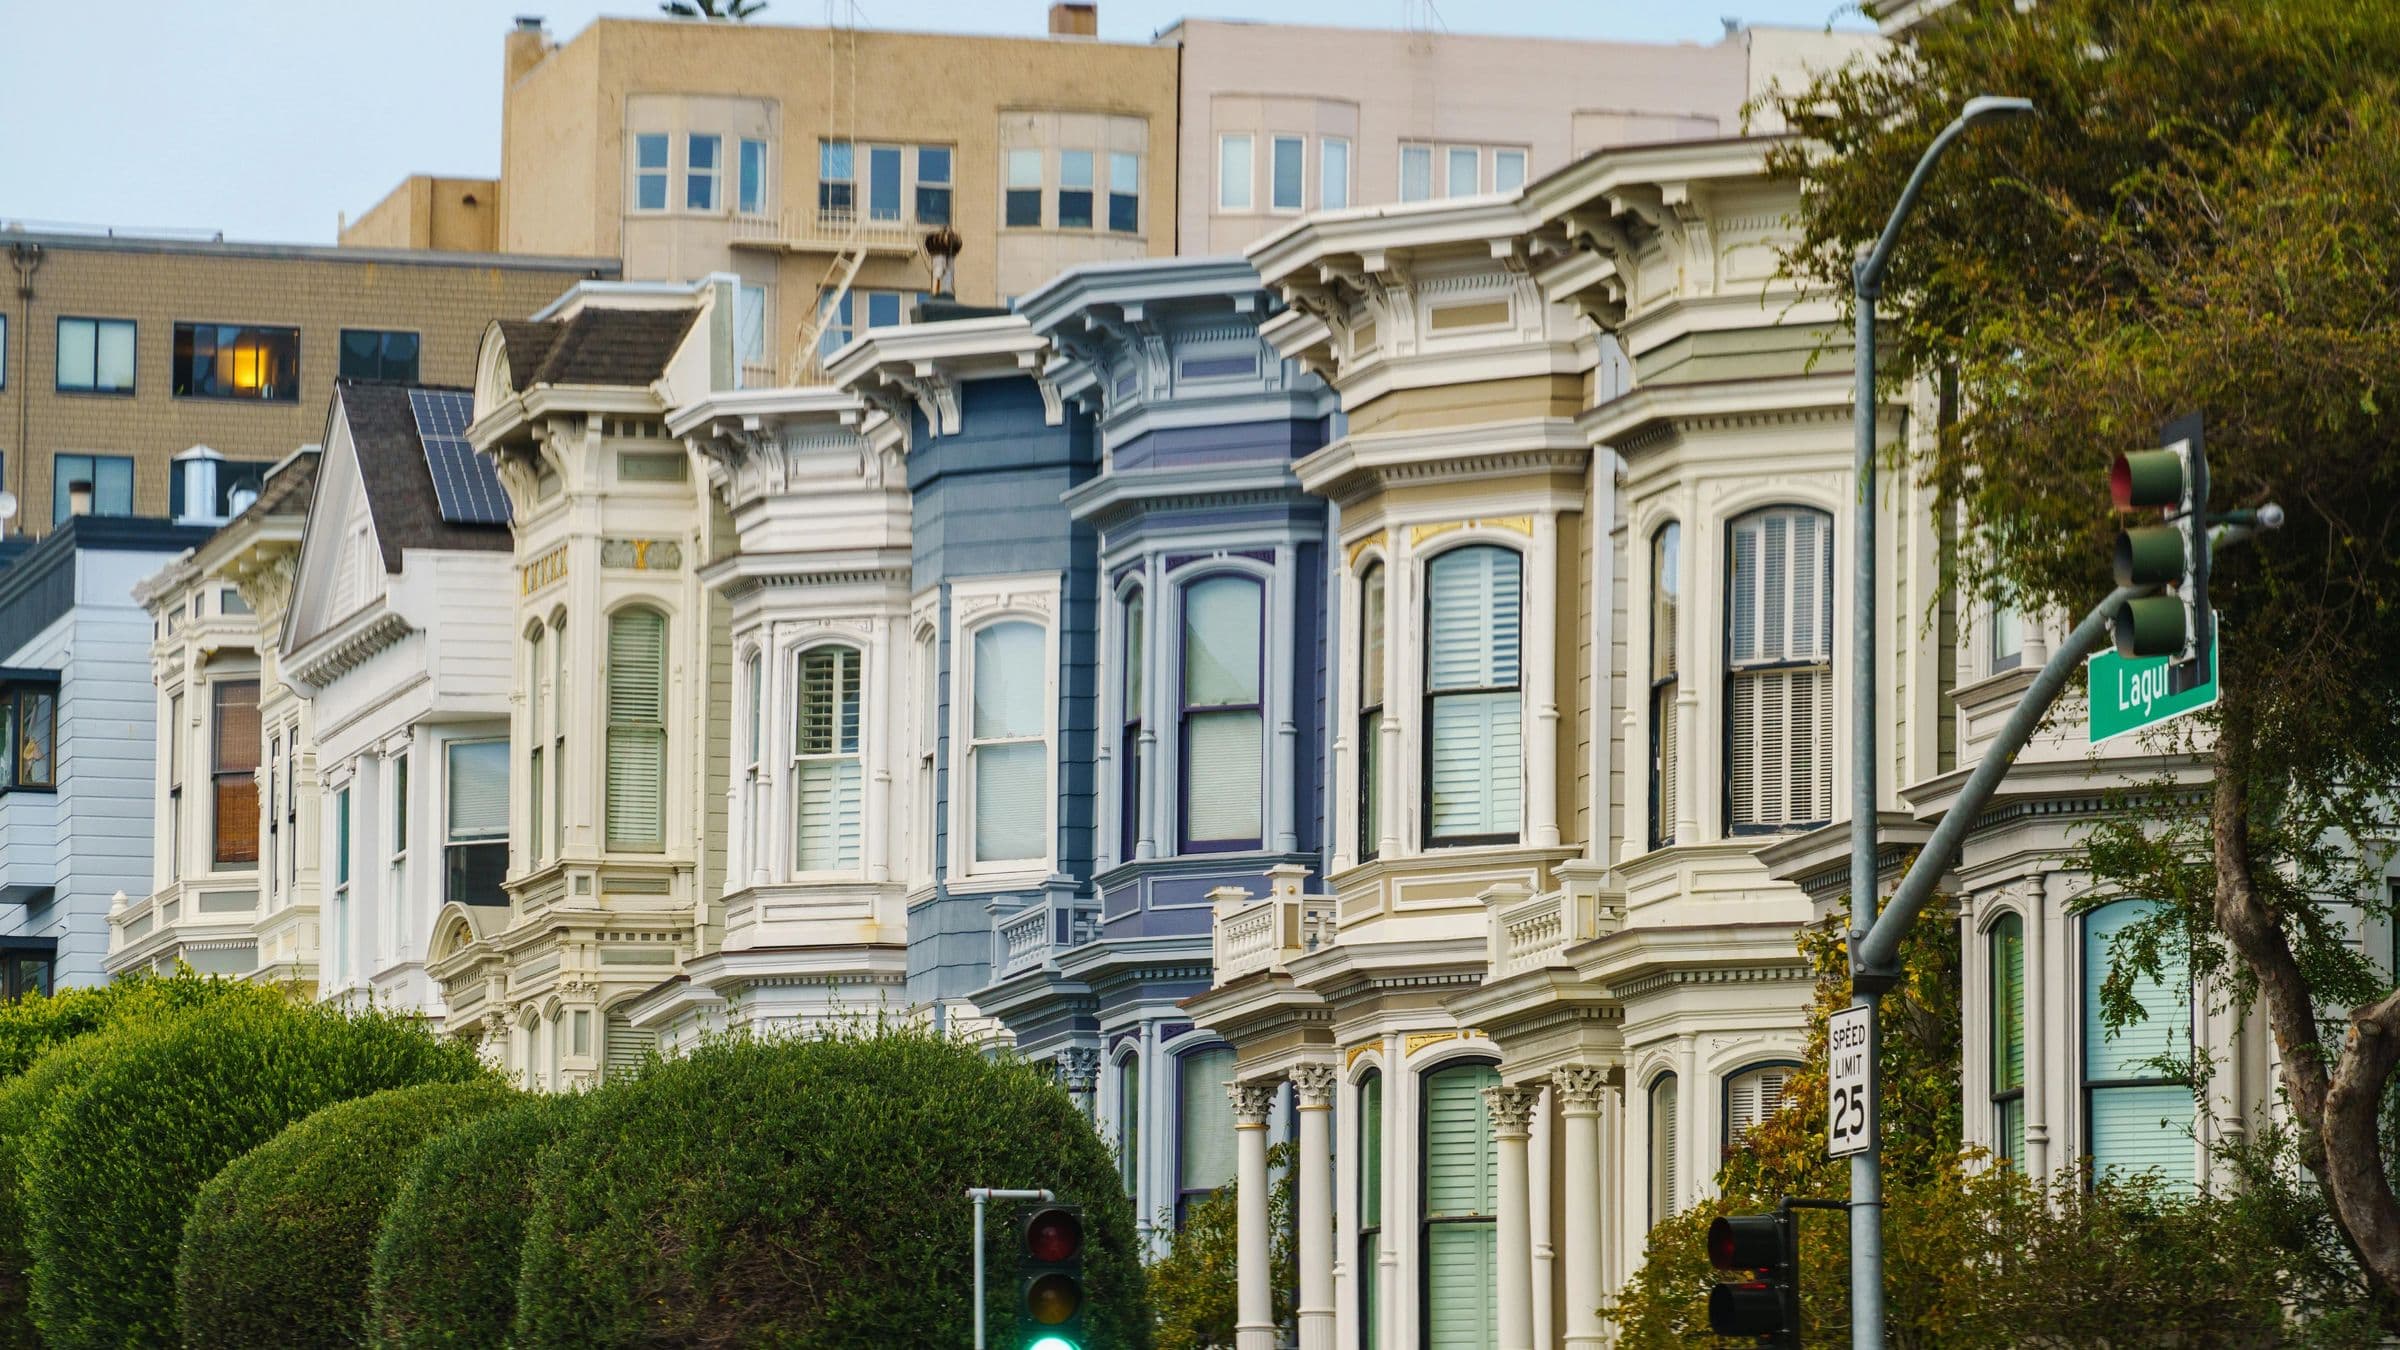
In San Francisco, the answer is not always obvious. Many of the city's two- to six-unit Victorian and Edwardian buildings are not condominiums but tenancy-in-common (TIC) properties.
- Condominium: you hold title to your own unit, plus a share of the common areas, governed by a homeowners association.
- Tenancy in common: you own an undivided share of the whole property. A TIC agreement gives you the right to occupy a particular unit and sets out how costs are split. The California Department of Real Estate describes TIC interests as "undivided interests, coupled with occupancy rights to particular units."
The difference matters most for financing. TIC buyers typically use specialized fractional loans, or share a single group loan with co-owners, which carries more risk. TIC homes can also take longer to resell. Some TIC buildings can later convert to condominiums, but San Francisco's conversion rules are restrictive: for example, the city's long-running condo-conversion lottery has been suspended in recent years. Get specific advice from a real estate attorney on any building you are considering.
Financing a condo
Lenders underwrite the building as well as the buyer. Before you write an offer, ask your lender about:
- Building approval. Some loan programs require the project to meet the lender's criteria: owner-occupancy levels, delinquencies, reserves, insurance and litigation.
- Small-building rules. Two- and three-unit condominiums are sometimes treated differently from larger buildings.
- The HOA questionnaire your lender will send the association, and how quickly the association answers it.
A building that cannot meet conventional criteria may still be financeable through a portfolio lender, usually on different terms.
The HOA documents California requires
When a California condominium is sold, the seller must give the buyer a defined set of association documents under Civil Code §4525. They include:
- the governing documents: CC&Rs, bylaws and rules;
- the association's most recent budget and financial disclosures;
- a statement of current assessments and any unpaid amounts;
- any approved assessment increases not yet due;
- notice of unresolved violations;
- any rental restrictions;
- board minutes from the previous 12 months, if requested;
- the most recent inspection report required under Civil Code §5551.
Read all of it. The minutes in particular often tell you what the financial statements don't: planned projects, disputes, insurance problems and repairs that have been put off.
Reserves and special assessments
California's Civil Code §5550 requires associations to commission a reserve study at least once every three years, including a visual inspection of major components, and to review it every year. The study estimates what roofs, siding, elevators, waterproofing and other major components will cost to repair or replace, and how much the association should be saving.
Compare the reserve balance with what the study says is needed. A significant shortfall means owners will eventually pay the difference, through higher dues, a special assessment or both. Ask directly whether any special assessment is being discussed.
Earthquakes, retrofit and insurance
Retrofit. San Francisco's Mandatory Soft Story Program, created in 2013, applies to wood-frame, multi-family buildings with five or more units and two or more stories that were permitted for construction before 1 January 1978. If your building is covered, confirm with the Department of Building Inspection that the work has been completed, and ask how it was paid for.
Insurance. The association's master policy covers the building as defined in the CC&Rs. You will need your own policy, often called an HO-6, for your interior and contents. Standard condo policies generally do not cover earthquake damage. The California Earthquake Authority offers a separate condo-unit policy through participating insurers, which can include loss assessment coverage for your share of HOA assessments after a quake. Check whether the association itself carries earthquake cover.
How San Francisco sales work
Many San Francisco listings come with a disclosure package, often including the seller's pre-sale inspection reports, prepared before offers are due. Reading it with your agent before you write an offer lets you make a stronger offer with fewer contingencies, while still knowing what you are buying. Many homes are also listed with a set offer date. The list price is a starting point, and recent comparable sales tell you far more.
Closing costs and taxes to plan for
- Property tax. Under Proposition 13, your assessed value resets to market value when you buy. The base rate is 1% plus voter-approved local charges, and annual increases are generally capped at 2%. Expect a separate supplemental tax bill after you close.
- Transfer tax. San Francisco charges a tiered transfer tax, for example $3.40 per $500 of value between $250,000 and $1 million, and $3.75 per $500 from $1 million to $5 million. Who pays is negotiable and set out in the contract.
- Title, escrow, lender fees and HOA transfer fees, which vary by transaction.
Before you write an offer
- Confirm the ownership type: condo or TIC.
- Confirm the building works with your loan.
- Read the §4525 documents, minutes first.
- Compare reserves with the reserve study.
- Check retrofit status and insurance, including earthquake cover.
- Review the disclosure package and inspections.
Where to look
Condominiums are spread across the city, from Victorian conversions to high-rises. Our guide to the best San Francisco neighborhoods for condo buyers compares the main areas, and Lance's neighborhood pages cover the Castro & Duboce Triangle, Mission Dolores, Noe Valley and Bernal Heights. Lance has worked in San Francisco since the 1990s. Ask him about a building before you write an offer.
General information only, not legal, lending or insurance advice. Confirm the details for any property with your attorney, lender and insurer. Last reviewed October 2026.
Sources: California DRE – TIC guidelines; California Civil Code §4525 summary; Community Associations Institute – California reserve requirements (Civil Code §5550); SF Department of Building Inspection – Mandatory Soft Story Program; California Earthquake Authority – Condo unit policies; California BOE – Publication 29; City and County of San Francisco – Transfer tax; Andy Sirkin – San Francisco condo conversion rules. Accessed 23 October 2026.
A question about your own situation?
Lance is glad to talk it through, with no obligation.
Get in touch