Buying a Duplex or 2–4 Unit Building in San Francisco
Financing, rent control, tenants and the numbers to run before you buy.
By Lance Fulford6 min read
Buying a duplex, triplex or fourplex in San Francisco can do something a single-family home can’t: put a roof over your head and rent income in your pocket from the same purchase. It is also one of the most rule-heavy purchases in the city. Rent control, tenant protections, lending rules and building condition all affect what a 2–4 unit building is really worth to you. This guide covers how financing works, how to judge the rent roll, what changes when the building comes with tenants, and the mistakes buyers make most often.
Why buyers choose a 2–4 unit building
- Owner-occupants live in one unit and rent the others, so the rent offsets part of the mortgage.
- Families buy together: parents in one flat, adult children in another.
- Small investors want a building they can understand and manage themselves.
Buildings with up to four units are still financed as residential property, which is why the 2–4 unit range is the sweet spot for owner-occupants. Five units and up moves into commercial lending.
Financing a 2–4 unit building
Owner-occupied conventional loans
If you will live in one of the units, conventional financing is far more accessible than it used to be. Since the weekend of November 18, 2023, Fannie Mae’s Desktop Underwriter allows up to 95% loan-to-value on owner-occupied purchases of two-, three- and four-unit homes, up from 85% for two units and 75% for three to four units before. In practice, that can mean as little as 5% down for qualifying buyers, subject to credit, reserves and the lender’s own rules.
Loan limits are higher for more units
Conforming loan limits are set by unit count. For 2026, FHFA’s baseline limits are $832,750 for one unit, $1,066,250 for two, $1,288,800 for three and $1,601,750 for four, and limits are higher still in high-cost areas such as the Bay Area. Ask your lender for the exact San Francisco limit for the unit count you are buying; above it, you are into jumbo financing.
Investor loans
If you won’t live in the building, expect a larger down payment and stricter terms. Lenders will look closely at the actual leases and the building’s income.
Rental income and qualifying
Lenders typically count only part of the rental income toward your qualifying income, and they will want leases and an appraisal that supports the rents. Don’t assume the full rent roll will qualify you.
Run the numbers the right way
A building is only a good buy if the numbers work with realistic assumptions. Build your own simple pro forma:
| Line | What to use |
|---|---|
| Rental income | Actual current rents from signed leases, not “market rent” projections |
| Vacancy | A realistic allowance for turnover |
| Property tax | Based on your purchase price (reassessed at sale), not the seller’s current bill |
| Insurance | A quote for the building, including liability as a landlord |
| Water, sewer, garbage | Often paid by the owner in older buildings |
| Repairs and reserves | Older San Francisco buildings need regular roof, plumbing, electrical and paint work |
| Management | Your time, or a property manager’s fee |
| Rent Board fees | Annual fees apply to covered units |
Then compare the result with your mortgage payment. Many owner-occupied buildings in San Francisco don’t fully pay for themselves on day one; the rent offsets the cost rather than covering it. That can still be a good outcome, as long as you go in knowing it.
Rent control and tenants: the part that changes everything
Most 2–4 unit buildings in San Francisco are older, and that matters:
- Rent increase limits. Under the City’s guidance, many units in buildings built on or before June 13, 1979 have both rent control and eviction protection. Rent increases on covered units are limited to an annual percentage set by the Rent Board.
- Just-cause eviction. Tenants can generally only be evicted for a reason listed in the Rent Ordinance. Owner move-in is one such reason, but it comes with conditions and, in many cases, relocation payments. Confirm the rules and costs with the Rent Board and an attorney before you count on it.
- Newer buildings built after mid-1979 generally aren’t subject to the local rent increase limits, but they still carry eviction protection, and California’s statewide Tenant Protection Act may apply.
The practical effect: if you want to live in the building, a vacant unit, or one being delivered vacant, is worth more to you than an occupied one. A tenant-occupied unit at a below-market rent may stay that way for many years. Price the building on the rents it actually has.
Due diligence specific to small buildings
- Estoppel certificates from each tenant, confirming rent, deposits and any side agreements.
- Rent Board records for past petitions, evictions and buyouts on the property.
- Permit history from the Department of Building Inspection. Confirm the legal unit count matches what you are buying.
- Unpermitted units. A ground-floor in-law unit without permits affects financing, insurance and resale. San Francisco has a unit legalization program for units built before 2013, but it involves design work, permits and fees.
- Inspections: a general inspection, pest report, and sewer lateral inspection, plus roof and foundation reviews where needed.
- Seismic requirements. Check whether the building is subject to the City’s mandatory soft-story retrofit program and whether any required work was completed.
- Condo conversion potential. If you hope to convert to condominiums one day, check eligibility first; conversion is tightly limited. See Condo vs TIC in San Francisco.
Common buyer mistakes
- Paying for projected rents. Value the building on today’s leases.
- Assuming you can move in. If every unit is occupied, owner move-in is a legal process with conditions and costs, not a formality.
- Skipping the permit history. An extra unit that isn’t legal can cause problems with your loan, your insurance and your exit.
- Underestimating repairs. San Francisco’s older buildings rarely need nothing.
- Getting the wrong pre-approval. Make sure your lender has approved you for the specific unit count and occupancy.
Where 2–4 unit buildings are
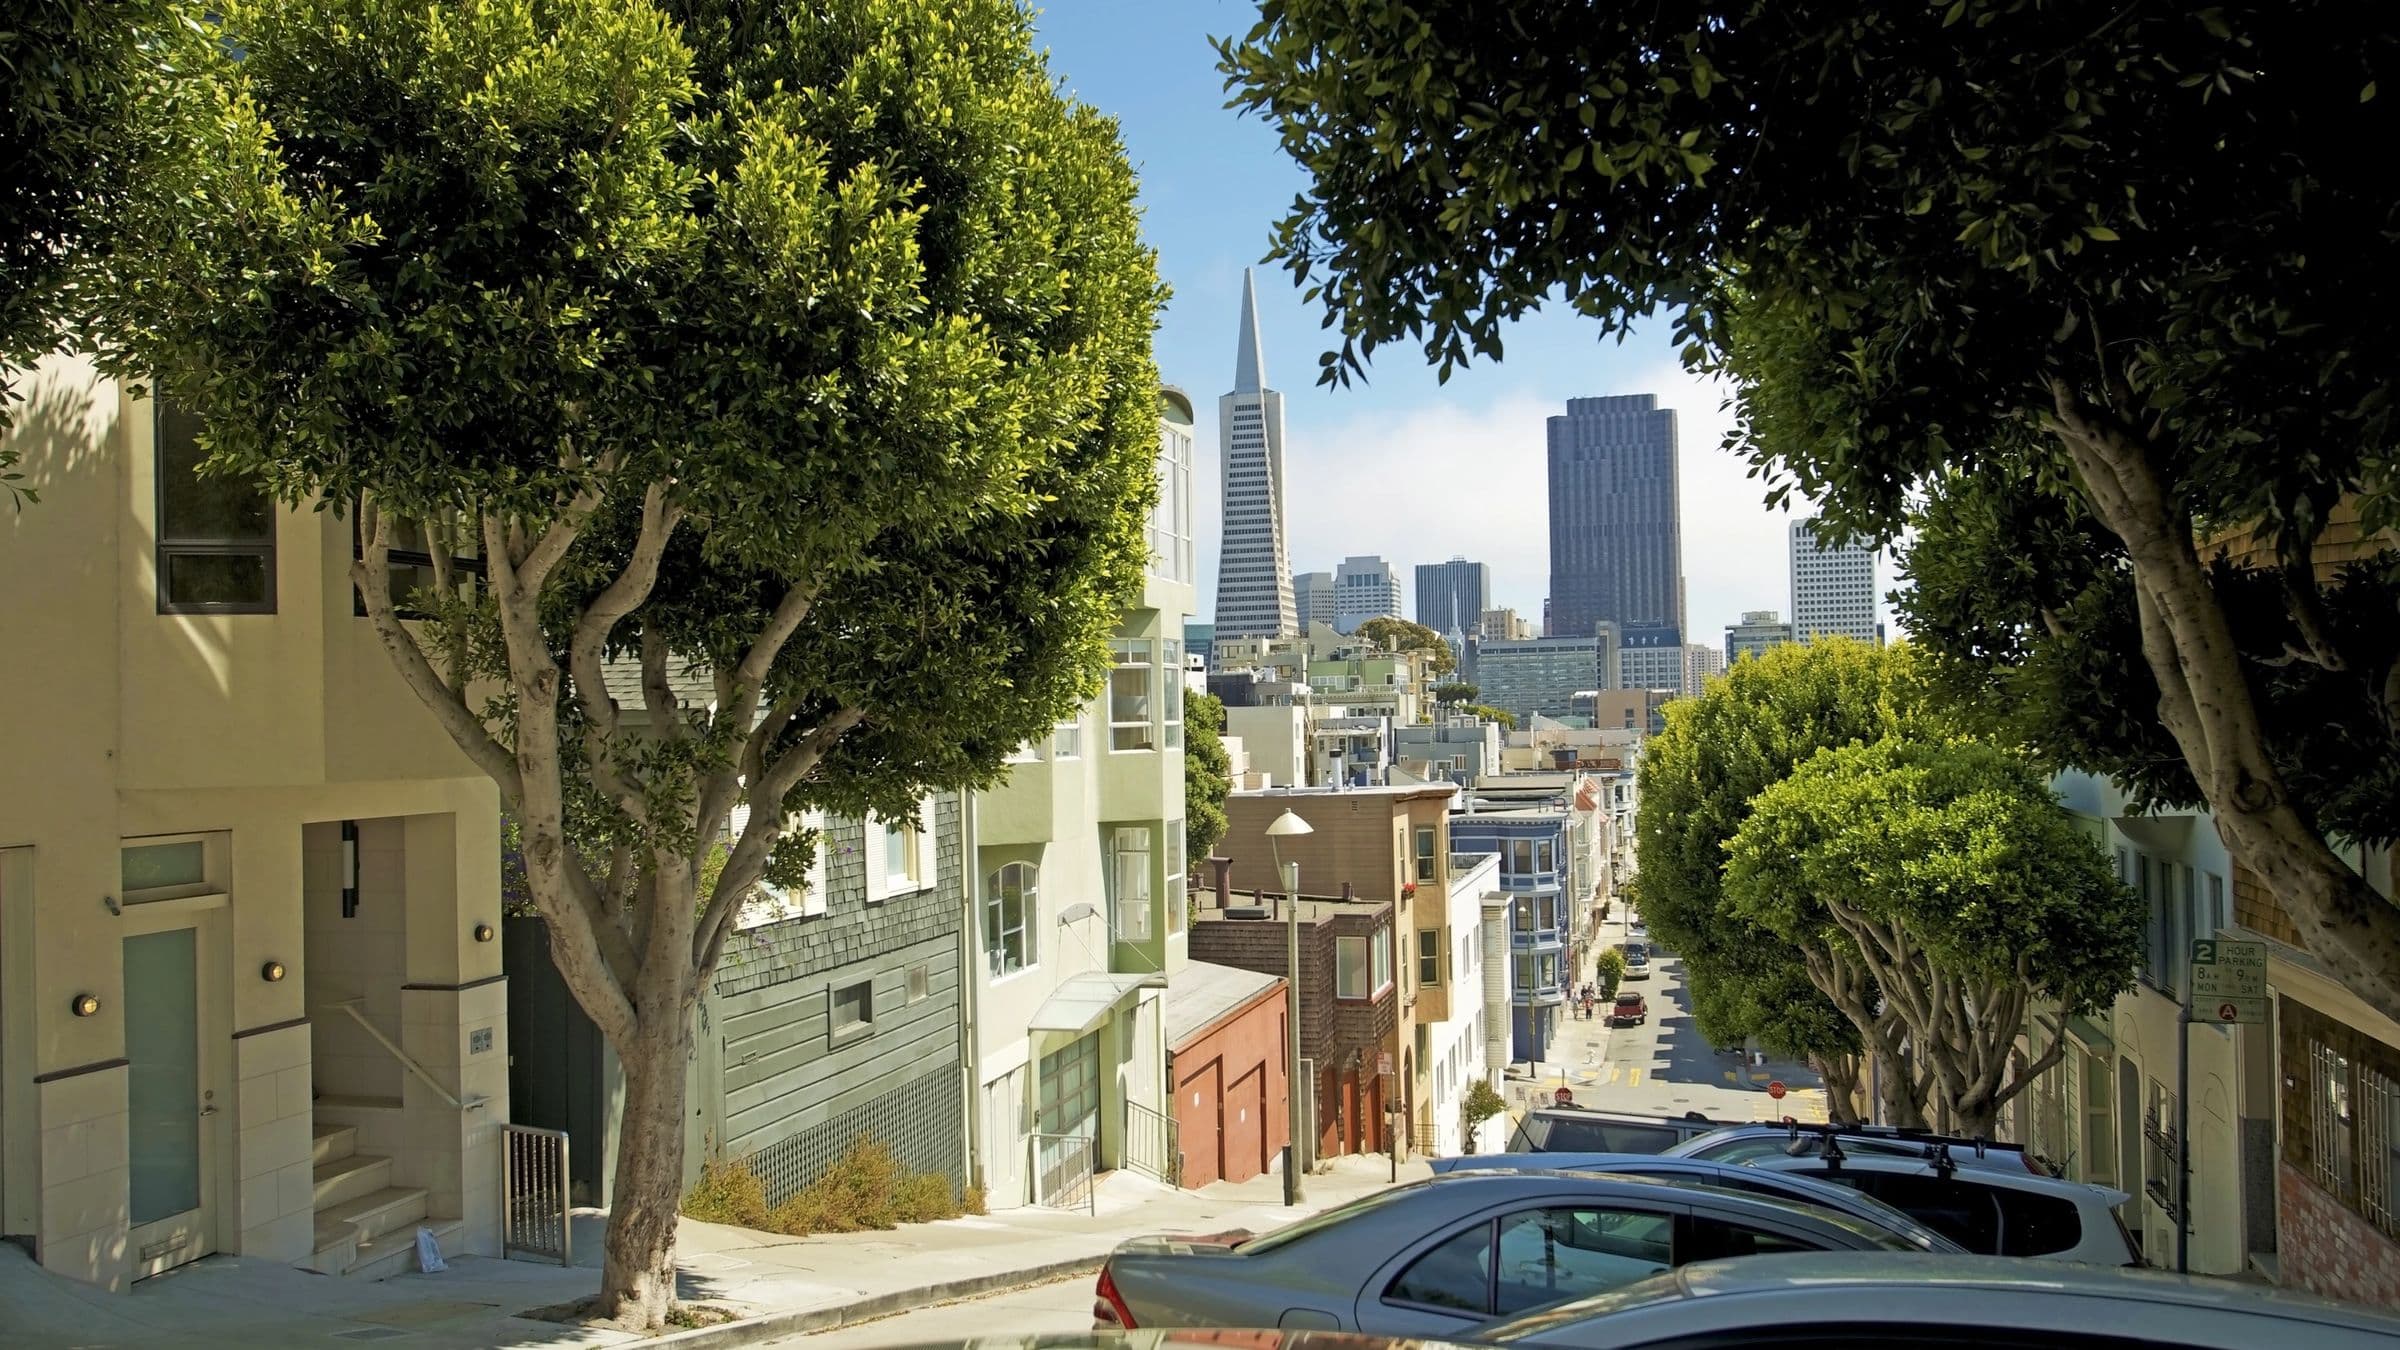
Small multi-unit buildings are spread across the city, with many Victorian and Edwardian flats in Noe Valley, the Castro and Eureka Valley and the Haight and Cole Valley, and two- and three-unit buildings throughout the Richmond District.
Lance’s record includes 16 closed sales of multi-unit buildings in San Francisco, from duplexes in Noe Valley and Pacific Heights to a fourplex in the Inner Richmond. See them on his past sales page.
Frequently asked questions
Can I buy a duplex in San Francisco with 5% down?
Possibly. Since November 2023, Fannie Mae has allowed up to 95% loan-to-value on owner-occupied two- to four-unit purchases through Desktop Underwriter. Your credit, reserves, the loan amount and your lender’s own rules decide whether you qualify.
Are duplexes in San Francisco rent controlled?
Often, yes. Many units in buildings built on or before June 13, 1979 are covered by rent increase limits and just-cause eviction rules. Newer units generally have eviction protection only. Check each unit with the Rent Board.
Can I move into a tenant-occupied unit after I buy?
Owner move-in is a recognized just cause for eviction, but it comes with conditions, waiting periods and, often, relocation payments. Get legal advice before you buy on that assumption.
Does rental income help me qualify for the mortgage?
Usually partly. Lenders typically count a portion of documented rental income. Ask your lender how they will treat the leases on the specific building.
What is the difference between buying 2–4 units and 5 or more?
Up to four units is financed as residential property, with owner-occupied programs available. Five units and more generally needs commercial financing.
Talk to Lance
Looking at a duplex or small building, or thinking about selling one? Connect with Lance. If you own one now, you can also ask what it would sell for.
General information only, not legal, tax or lending advice. Rent and eviction law and loan programs change often; confirm every rule for a specific property with the Rent Board, your attorney and your lender. Last reviewed November 2026.
Sources: Fannie Mae, DU Version 11.1 Release Notes (Nov. 2023): maximum LTV for 2–4 unit principal residences; FHFA, 2026 conforming loan limits; City and County of San Francisco, Learn about San Francisco rental laws; SF Rent Board, Costa-Hawkins partial exemption; City and County of San Francisco, Legalize a unit in your home. Accessed 1 November 2026.
A question about your own situation?
Lance is glad to talk it through, with no obligation.
Get in touch